
Wafer Level Packaging Market Share, Growth & Demand by 2034
Coverage: By Packaging Type (Flip Chips, Fan-out Wafer Level Packaging, Through-Silicon Via); Process Type (Electrochemical Deposition (ECD), Physical Vapor Deposition (PVD), Etch, Chemical Vapor Deposition (CVD), Chemical Mechanical Planarization (CMP)); Application (Electronics and Semiconductor, Aerospace and Defense, Automotive, Others), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00015725
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 28, 2026


2025 Market Size
US$ 10.39 Bn
Base year value
2034 Forecast
US$ 22.31 Bn
Projected by 2034
CAGR 2026-2034
8.86 %
Growth rate
Addressable Market
US$ 146.41 Bn
(2026-2034)
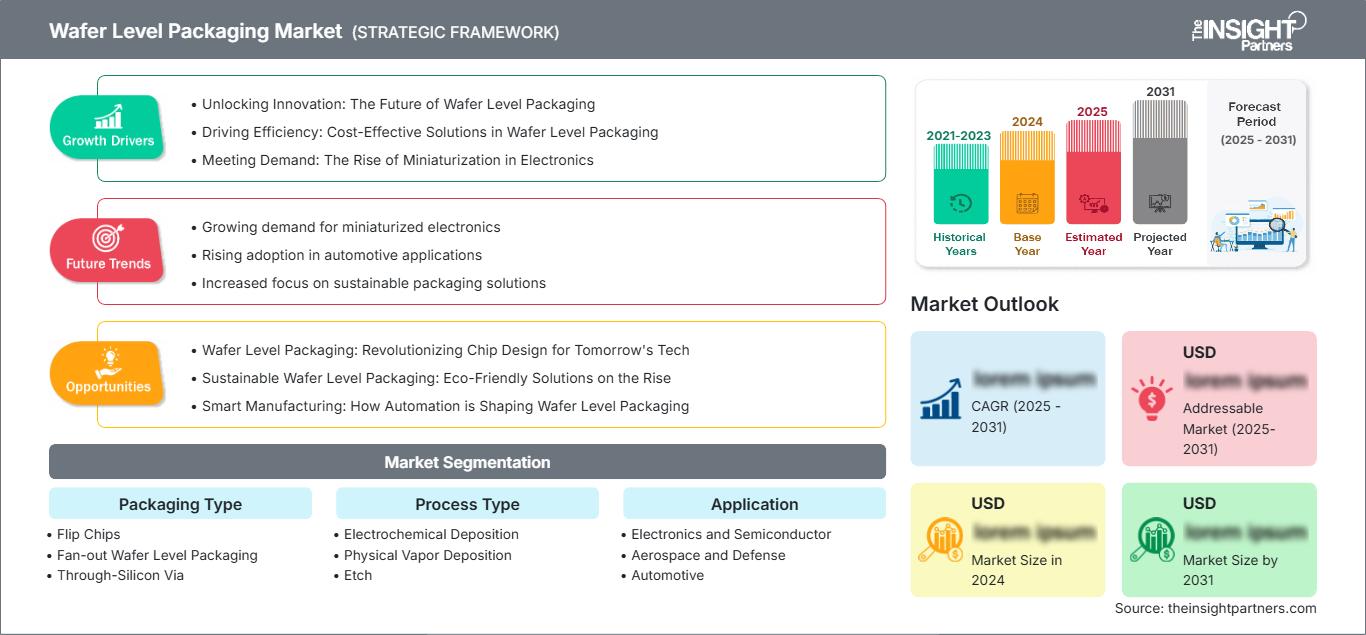
The wafer level packaging market was valued at US$ 10.39 Billion in 2025 and is projected to reach US$ 22.31 Billion by 2034, registering a CAGR of 8.86% during 2026–2034. Expansion reflects increasing semiconductor integration, compact device requirements, the adoption of advanced interconnects, and rising deployment across computing, communications, automotive, industrial, and aerospace electronics. The market is also benefiting from higher functionality requirements within increasingly constrained package footprints.
North America represents a strategically important manufacturing and technology base, with the wafer-level packaging market size expected to expand at an estimated 8.2–8.7% CAGR during 2026–2034. Semiconductor reshoring, investments in advanced packaging, artificial intelligence infrastructure, and government-backed supply chain localization are strengthening regional demand. Increasing requirements for heterogeneous integration and high-density interconnects are encouraging equipment, materials, foundry, and outsourced semiconductor assembly and test participants to expand capabilities across the United States and Canada.
Wafer Level Packaging Market Assessment and Insights
- North America: The region is estimated to account for 28–32% share in 2025, supported by semiconductor investment and advanced packaging localization, while growing at a CAGR of 8.2–8.7% between 2026–2034.
- US: The US represents approximately 78–82% of North America's 2025 share and is expected to expand at a CAGR of 8.5–9.0% through 2034.
- Europe: Europe is estimated at 20–24% share in 2025 and is projected to grow at a CAGR of 7.7–8.2%, led by Germany, France, Italy, Spain, and the UK.
- Asia Pacific: Asia Pacific is estimated to hold 33–37% share in 2025 and expand at a CAGR of 9.2–9.7%, led by China, Japan, South Korea, Taiwan, and India.
- Largest Segment: Fan-out wafer level packaging is estimated at 38–42% market share in 2025, with a CAGR of 9.8–10.4% through 2034.
- High Growth Segment: Through-silicon via is estimated at 20–24% market share in 2025 and is projected to record a CAGR of 10.5–11.2% through 2034.
- Key companies analyzed in detail: Amkor Technology, Inc.; Applied Materials, Inc.; Brewer Science, Inc.; Deca Technologies; Fujitsu Limited; Infineon Technologies AG; Lam Research Corporation; Siliconware Precision Industries Co., Ltd.; STATS ChipPAC Ltd.; Tokyo Electron Limited.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The wafer level packaging market has evolved from conventional wafer-level chip-scale applications toward architectures supporting higher input/output density, shorter interconnect paths, and heterogeneous integration. Fan-out structures have expanded beyond mobile applications, while through-silicon vias increasingly address three-dimensional integration requirements. Advances in equipment for deposition, etching, planarization, and lithography are simultaneously improving process control. Production strategies increasingly emphasize yield, warpage management, thermal performance, and finer redistribution layers.
Looking ahead, the wafer level packaging market report indicates that investment is expected to broaden across North America, Asia Pacific, and selected European semiconductor clusters as governments seek resilient domestic supply chains. Artificial intelligence accelerators, high-performance computing, automotive electronics, and edge devices are increasing the demand for compact, thermally efficient packages. Regulatory incentives supporting semiconductor manufacturing are likely to improve regional capacity economics, while tighter process tolerances will encourage investments in metrology, materials engineering, advanced process control, and specialized packaging equipment.
Wafer Level Packaging Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 10.39 Billion |
| Market Size by 2034 | US$ 22.31 Billion |
| Global CAGR (2026 - 2034) | 8.86% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Wafer Level Packaging Market Analysis
The wafer level packaging market growth is being shaped by the need to improve electrical performance without proportionally increasing package dimensions. The choice of semiconductor packaging has now shifted to wafer level packaging, where shorter interconnects, reduced parasitics, and denser routing enable faster devices. The industry comprises integrated device manufacturers, foundries, outsourced semiconductor assembly and testing facilities, equipment makers, materials producers, and design companies. It is becoming increasingly supply-constrained by advanced deposition, etch, planarization, mold, and redistribution technology capability, with equipment availability and process yield becoming key drivers for scalability.
Moreover, demand is becoming increasingly diverse across automotive, communications, industrial, and aerospace applications. Automotive electronics require packaging that can withstand thermal cycling, vibration, and limited space, whereas mobility devices require a low profile and energy efficiency. Thus, semiconductor firms are balancing package density with yield & reliability. The growing complexity of chips is driving the importance of process integration, as defects in wafer level packaging will impact multiple chips at once.
The wafer level packaging market analysis increasingly centers on differentiated process capability rather than capacity alone. Amkor Technology, Inc. is building up its capabilities within the US advanced packaging segment, while Applied Materials, Inc. and Lam Research Corporation compete on their equipment platforms to meet deposition, etch and associated process needs. Tokyo Electron Limited is significant within semiconductor process equipment, whereas Brewer Science, Inc. provides materials and temporary bonding services. Deca Technologies focuses on fan-out architectures and advanced redistribution technologies.
Regional manufacturing presence and customer qualification cycles also play an important role in the competitive positioning. Fujitsu Limited and Infineon Technologies AG generate application-specific demand through their computing, automotive, industrial and connectivity semiconductor products. Siliconware Precision Industries Co., Ltd. and STATS ChipPAC Ltd. are contributing assembly and test know-how, while process-intensive players distinguish themselves based on equipment precision and materials capabilities. Increased investment in high-density packaging, automation, yield enhancement and local manufacturing creates opportunities for those players who can support multiple manufacturing steps.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Wafer Level Packaging Market: Strategic Insights
Regional Insights
North America wafer level packaging market
North America is estimated to hold 28–32% of the wafer level packaging market share in 2025 and is projected to grow at a CAGR of 8.2–8.7% during 2026–2034. The United States dominates regional demand due to its design capabilities in semiconductors, artificial intelligence, and defense electronics, and its growing focus on domestic advanced packaging capabilities. Incentives and investments from the government and the private sector are fostering the development of advanced packaging and equipment capabilities, as well as supplier localization. Canadian contributions to the regional ecosystem include semiconductor technology, specialized electronics, and materials.
The regional ecosystem is becoming increasingly inclined towards reduced reliance on foreign packaging capacity for strategically significant chips. Amkor Technology, Inc. revealed plans to develop an advanced packaging campus in the US in Arizona, to be funded with US$7 billion over two phases. The project aims to create advanced packaging capabilities at high volumes in the United States. The demand will be driven by AI accelerators, networking devices, aerospace electronics, and automotive computing.
U.S. wafer level packaging Market
The US accounts for approximately 78–82% of North America's 2025 wafer level packaging market share and is expected to grow at a CAGR of 8.5–9.0% through 2034. Public incentives, semiconductor localization, and AI infrastructure are major structural factors. Packaging investments are increasingly linked to national supply chain resilience and advanced computing requirements.
Corporate presence includes Amkor Technology, Inc., Applied Materials, Inc., Lam Research Corporation, and other equipment and packaging companies. Uses for such semiconductor components continue to grow, from consumer and communications devices to artificial intelligence, automotive, military, and HPC chips. The company expects the Arizona site to begin manufacturing in early 2028.
Europe wafer level packaging Market
Europe is estimated to represent 20–24% share of the wafer level packaging market in 2025 and is projected to expand at a CAGR of 7.7–8.2%. Germany drives regional efforts through automotive electronics, industrial semiconductors, and fabrication infrastructure. The UK contributes research and design capability along with compound-semiconductor expertise, while France contributes aerospace, defense, automotive, and electronics applications.
Italy and Spain add additional demand through automotive, industrial automation, telecommunications, and electronics fabrication applications. Semiconductors are becoming a policy focus, particularly with an emphasis on semiconductor resilience and the capability for domestic production in the region. Germany continues to be the dominant country, backed by its large automotive and industrial infrastructure base. Future demand will likely prefer small, reliable package formats that can manage power, sensing, connectivity, and edge computing.
APAC wafer level packaging Market
APAC is estimated to hold 33–37% share of the wafer level packaging market in 2025 and is expected to grow at a CAGR of 9.2–9.7%. The primary regional ecosystem includes China, Japan, South Korea, Taiwan, India, and Australia. Taiwan and South Korea continue to be important in semiconductor fabrication and integration.
Domestic semiconductor investments in China drive packaging localization, while Japan offers equipment, materials, and manufacturing precision capabilities. South Korea derives its strength from its memory and advanced semiconductor integration, while India has been working to build a semiconductor ecosystem in its manufacturing sector. Australia is still smaller but offers research and specialized technologies. The combination of all these elements makes APAC the top geographic growth region.
Middle East & Africa wafer level packaging Market
The Middle East and Africa wafer level packaging market demand is projected to expand at a CAGR of 7.0–7.5%, supported by digital infrastructure, electronics localization, industrial automation, and semiconductor-related investment. Saudi Arabia and the UAE are leading markets because of technology diversification programs and infrastructure spending, while South Africa contributes research and electronics capabilities.
In this respect, Saudi Arabia and the United Arab Emirates are aggressively building their digital infrastructure, data centers, and industrial capabilities, which are indirectly driving demand for sophisticated semiconductors. South Africa continues to be important for research and electronics, while the rest of MEA is good for long-term prospects tied to telecommunication, energy and industrial advancements. Growth will still be below APAC, North America and Europe but driven by infrastructure-led technology adoption.
Segmentation Analysis
Packaging Type
The Packaging Type segment of the wafer level packaging market is expected to expand at a CAGR of 9.0–9.4% during 2026–2034. Adoption is being influenced by requirements for smaller packages, higher I/O density, improved thermal behavior, and heterogeneous integration. Fan-out architectures provide design flexibility, while flip-chip remains important for high-performance connectivity, and TSV supports vertically integrated designs.
- Flip Chips: Flip Chips remain highly relevant in high-performance semiconductor applications because direct interconnection enables short electrical paths, efficient heat transfer, and high-density I/O. Their established manufacturing ecosystem also supports broad customer qualification.
- Fan-out Wafer Level Packaging: Fan-out Wafer Level Packaging benefits from substrate reduction, flexible routing, and compact form factors. Its applicability across mobile processors, connectivity devices, automotive electronics, and emerging heterogeneous architectures strengthens strategic importance.
- Through-Silicon Via: Through-Silicon Via enables vertical electrical connections through silicon, supporting stacked memory, three-dimensional integration, and high-bandwidth architectures. Increasing computing density and shorter interconnect requirements reinforce its long-term strategic relevance.
Process Type
The Process Type segment of the wafer level packaging market is projected to grow at a CAGR of 8.4–8.8% through 2034. Process precision is becoming increasingly important as redistribution layers become finer and package architectures more complex. Deposition, etching, planarization, and related wafer-level steps must maintain uniformity and yield while controlling contamination, warpage, and dimensional variation.
- Electrochemical Deposition: Electrochemical Deposition remains strategically important for forming conductive layers and redistributing structures, particularly where uniform metal thickness and controlled electrical characteristics are essential for advanced packaging yields.
- Physical Vapor Deposition: Physical Vapor Deposition supports thin-film formation and metallization requirements, with demand driven by increasingly sophisticated interconnect stacks and tighter process windows in wafer-level semiconductor manufacturing.
- Etch: Etch processes are essential for defining patterns and selectively removing material. Greater structural complexity increases requirements for precision, selectivity, repeatability, and process control across advanced packaging flows.
- Chemical Vapor Deposition: It enables controlled thin-film deposition and the formation of protective structures. Its importance rises as packaging architectures require improved material uniformity and carefully engineered interfaces between multiple process layers.
- Chemical Mechanical Planarization: It supports surface uniformity prior to subsequent process steps. Increasing multilayer integration makes planarization control important for yield, alignment, interconnect reliability, and wafer-level process consistency.
Application
The Application segment is anticipated to grow at a CAGR of 8.8–9.2% through 2034. Electronics and semiconductor applications remain the principal driver of demand, while aerospace, defense, and automotive systems increasingly require compact, reliable packages capable of withstanding demanding electrical and environmental conditions.
- Electronics and Semiconductor: Electronics and Semiconductor applications remain central because smartphones, computing devices, connectivity equipment, sensors, and AI hardware require increasing functionality within smaller package footprints.
- Aerospace and Defense: Aerospace and Defense applications prioritize reliability, thermal stability, radiation tolerance, and compact electronics. Qualification requirements create longer design cycles but can support durable demand for specialized packaging technologies.
- Automotive: Adoption is expanding as electronic content increases across electric vehicles, advanced driver assistance systems, infotainment, power management, and vehicle computing architectures. Reliability under thermal cycling remains a critical selection criterion.
Opportunity Snapshot
| Segment Name | Revenue Contribution | Trend Tag | Adoption Stage |
| Electronics and Semiconductor | High | AI Computing | Mature |
| Aerospace and Defense | Medium | Mission Electronics | Scaling |
| Automotive | High | Vehicle Computing | Scaling |
Wafer Level Packaging Market Growth Drivers and Impact Analysis
AI and High-Performance Computing Package Density
AI and high-performance computing are putting pressure on semiconductor performance demands at a rate that conventional package scaling alone cannot meet. The advantages of advanced wafer-level architectures include smaller interconnect lengths, higher routing density, and integration of different functional blocks on smaller areas. These demands influence equipment suppliers, materials vendors, foundries, and outsourced assembly houses, as increased complexity requires better process control and yields. AI infrastructure also increases the economic value of the packaging technology, enabling the companies to invest in expensive deposition, etching, planarization, bonding, and inspection equipment. In its August 2026 report, Applied Materials, Inc. stated that advanced packaging revenues would increase by more than 70% in 2026 due to strong demand from AI infrastructure.
Semiconductor Supply-Chain Localization
The government and semiconductor companies have begun exploring geographically diversified packaging capabilities, recognizing that semiconductor manufacturing alone does not ensure supply chain resilience. Therefore, advanced packaging has become a strategically manufactured product rather than a downstream service. Localization drives have helped make investments in equipment, materials, facilities, and labor skills, especially in the U.S., parts of Europe, and Asia. This development presents an opportunity for suppliers that can offer local qualifying processes while maintaining global process consistency. It affects suppliers beyond packaging suppliers, as local packaging capabilities reduce logistics distance, provide continuity for strategic semiconductor programs, and facilitate collaboration between semiconductor designers and packaging engineers.
Automotive Electronics and Reliability Requirements
The demand for semiconductors within the automotive industry is growing since the number of sensors, processors, power management features, communication capabilities, and automated driving technologies used in modern automobiles is growing. Wafer-level integration could enable automobile companies to produce compact systems while ensuring electrical performance and thermal efficiency. Nevertheless, automotive qualification has stringent reliability requirements, as semiconductors must withstand thermal cycling, mechanical loads, moisture, and long lifetimes. These factors motivate semiconductor suppliers to focus on materials research, process control, failure analysis, and reliability validation rather than on volume growth. The market's impact is significant due to the long product lifecycles and strict qualification requirements in the automotive segment.
Wafer Level Packaging Market Future Trends
Chiplet Integration and Advanced Heterogeneous Architectures
The wafer level packaging market trends are increasingly moving toward chiplet-based architectures that combine multiple specialized dies within a single system. In addition to using only monolithic scaling, designers can decouple the compute, memory, connectivity, and acceleration functionality and combine them by using highly dense interconnect technology. This may result in higher design flexibility and potentially reduced time-to-market, but also raises the level of packaging complexity. As a consequence, future manufacturing processes should focus on patterning of redistribution layers, advanced bonding, thermal solutions, and automated inspection. Through-silicon vias and fan-out are expected to enable various elements of these architectures, based on bandwidth and power considerations, among others. The suppliers who can bring materials, processing equipment, and metrology solutions together into a manufacturing platform will be well positioned to benefit from the trend towards heterogeneous integration.
Panelization, Automation, and Yield-Oriented Manufacturing
Future manufacturing solutions will integrate both wafer-level manufacturing technologies and larger-area panel solutions where economically and technologically viable. Larger processing areas can increase throughput, while automation and process analytics can address the increased variation arising from the growing complexity of the packaging structure. The focus will shift from individual equipment performance to yield management across the deposition, etch, mold, redistribute, planarize, inspect, and test steps. Process Control will become increasingly relevant, especially with growing dimensional scale reduction and complex material stack sets. Manufacturers will rely on process analytics to detect defect mechanisms, optimize process recipes and minimize rework. This can lead to an increased need for equipment that enables closed-loop control and for materials with consistent physical characteristics in large-volume manufacturing environments.
Wafer Level Packaging Market Opportunities
Localized Advanced Packaging Ecosystems
The wafer level packaging market scope is expanding as countries establish semiconductor ecosystems that include packaging rather than focusing exclusively on front-end fabrication. Investors can focus on specializing in facilities, equipment services, materials, testing, and process development within the developing regional clusters. The best business prospects are expected to emerge where semiconductor design activities, government incentive schemes, engineering expertise, and anchor customers are present. North America is one of the most obvious investment choices owing to the presence of new domestic packaging capacity that can help implement strategic computing and defense systems projects. Asia-Pacific remains an attractive destination due to its scale and logistics, whereas Europe offers distinct business prospects in automotive and industrial semiconductors.
High-Density Automotive and Edge Electronics
The wafer level packaging market forecasts indicate attractive opportunities in automotive and edge computing applications where space, power, thermal performance, and reliability increasingly intersect. Package architectures suitable for highly integrated design will be useful for automotive domain controllers, advanced driver assistance systems, radar modules, imaging systems, and power management circuits. Edge computing devices, on the other hand, need to process data locally without relying on a continuous cloud connection due to the additional cost and delays. Investors and suppliers, therefore, should focus on packaging materials, thermal interfaces, fine-pitch interconnections, inspection, and reliability solutions geared towards harsh environments. Firms possessing both semiconductor packaging skills and application-specific qualifications could forge closer relationships with customers than suppliers of standard packaging processes alone. Extended development cycles within the automotive sector could generate sustainable revenues after successful qualification.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for