
OEM Coatings Market Trends, Size & Growth by 2034
Coverage: By Formulation (Powder And High Solid Coatings, Water-Borne Coatings, Solvent-Borne Coatings, Radiation Curable Coatings); End User Industry (Transportation, Consumer Products, Heavy Equipment And Machinery, Others) And , and by Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00005107
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 28, 2026


2025 Market Size
US$ 73.78 Bn
Base year value
2034 Forecast
US$ 118.08 Bn
Projected by 2034
CAGR 2026-2034
5.36 %
Growth rate
Addressable Market
US$ 869.96 Bn
(2026-2034)
The oem coatings market size is valued at US$ 73.78 Billion in 2025 and is projected to reach US$ 118.08 Billion by 2034, expanding at a CAGR of 5.36% from 2026 to 2034. Demand is shaped by vehicle production, industrial equipment manufacturing, consumer-product output, and increasing requirements for corrosion protection, appearance, durability, and process efficiency. Formulation innovation is increasingly focused on lower emissions, faster curing, improved transfer efficiency, and compatibility with diverse substrates.
North America remains a significant production and consumption base, with the oem coatings market size supported by automotive manufacturing, industrial machinery, transportation equipment, and reshoring-related investment. Regional growth is expected at a 4.9–5.5% CAGR through 2034, supported by modernization of manufacturing facilities and greater adoption of powder, high-solid, and water-borne technologies.
OEM Coatings Market Assessment and Insights
- North America represents a 28–32% oem coatings market share in 2025 and is expected to grow at a 4.9–5.5% CAGR between 2026–2034. Automotive manufacturing, industrial reshoring, transportation equipment, and machinery modernization underpin regional demand.
- US accounts for 80–84% of North American consumption in 2025 and is projected to expand at a 4.8–5.4% CAGR between 2026–2034, supported by automotive, machinery, and industrial investment.
- Europe holds a 25–29% share in 2025 and is projected to grow at a 4.5–5.1% CAGR through 2034. Germany, France, Italy, the UK, and Spain support demand through automotive and industrial manufacturing.
- Asia Pacific commands a 32–36% share in 2025 and is expected to record a 6.1–6.8% CAGR between 2026–2034. China, Japan, South Korea, and India remain leading production and application centers.
- Largest Segment is Transportation, representing a 40–44% market share in 2025 and expanding at a 5.5–6.0% CAGR between 2026–2034, reflecting extensive OEM coating consumption.
- High Growth Segment is Powder And High Solid Coatings, accounting for a 28–32% market share in 2025 and growing at a 6.0–6.6% CAGR through 2034.
- Key companies analyzed in detail: 3M Company, Akzo Nobel N.V., Axalta Coating Systems Ltd., BASF SE, Jotun A/S, Kansai Paint Co., Ltd., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., The Sherwin-Williams Company, and The Valspar Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Formulation technologies are moving towards reduced curing energies, reduced emissions of volatile organic compounds, reduced waste, and reduced application processes, while maintaining performance as well as appearance and anti-corrosive characteristics. The OEM customer is looking at the economic feasibility of the coating system, from booth usage, through to oven requirements, efficiency of application, rework and speed of the lines. Automated applications and digital color management are also adding to the link between formulation design and manufacturing efficiency.
Investment into the oem coatings market in the future will become increasingly focused on the expansion of manufacturing capacity in Asia Pacific, regionalization of technical centers, more sustainable resin systems, and application processes that have reduced process energy requirements. Regulatory pressure in Europe is driving water-borne, powder, high-solid, and radiation-curable coating systems, whereas North American manufacturers are focused on productivity and sustainability. Industrial regions in India, Southeast Asia, and Mexico also present other growth possibilities.
OEM Coatings Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 73.78 Billion |
| Market Size by 2034 | US$ 118.08 Billion |
| Global CAGR (2026 - 2034) | 5.36% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
OEM Coatings Market Analysis
The demand throughout the value chain is driven by the production of transportation, consumer products, and heavy equipment. Growth of the OEM coatings market is especially tied to coating-intensive production processes where corrosion resistance, aesthetics, substrate adhesion, and durability contribute to the quality of the end product. The resin producers, pigment producers, additive manufacturers, formulators, application equipment, and OEM paint shop all together determine system performance and economic characteristics.
Supply-side factors in the OEM coatings market become more dependent on resins, pigment prices, energy usage, solvent exposure, and regional logistics. OEMs need to balance global formulations with local raw material availability in order to meet cost and compliance requirements. Both water-based and high solid systems need formulating know-how due to viscosity, drying performance, moisture levels, substrate preparation, and application equipment that could impact productivity. Once a coating system is adopted in the OEM line, qualification becomes a barrier to change.
Competitive positioning depends on technology depth, worldwide manufacturing, technical services, customer qualification, and consistency of performance between plants. PPG Industries, Inc., BASF SE, Axalta Coating Systems Ltd., Akzo Nobel N.V., and The Sherwin-Williams Company have extensive product ranges that cover automotive and industrial segments. Nippon Paint Holdings Co., Ltd., and Kansai Paint Co., Ltd. build up the competitive landscape in Asia.
Investment in innovation involves lower-energy curing technologies, sustainable raw materials, digital formulation, and coating for electrified vehicles and advanced equipment. 3M Company is providing innovative surface and application technologies; meanwhile, Jotun A/S keeps its competitive strengths in the industrial and protective coating sector. The Valspar Corporation can benefit from the Sherwin-Williams' wider platform of manufacturing and logistics operations.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
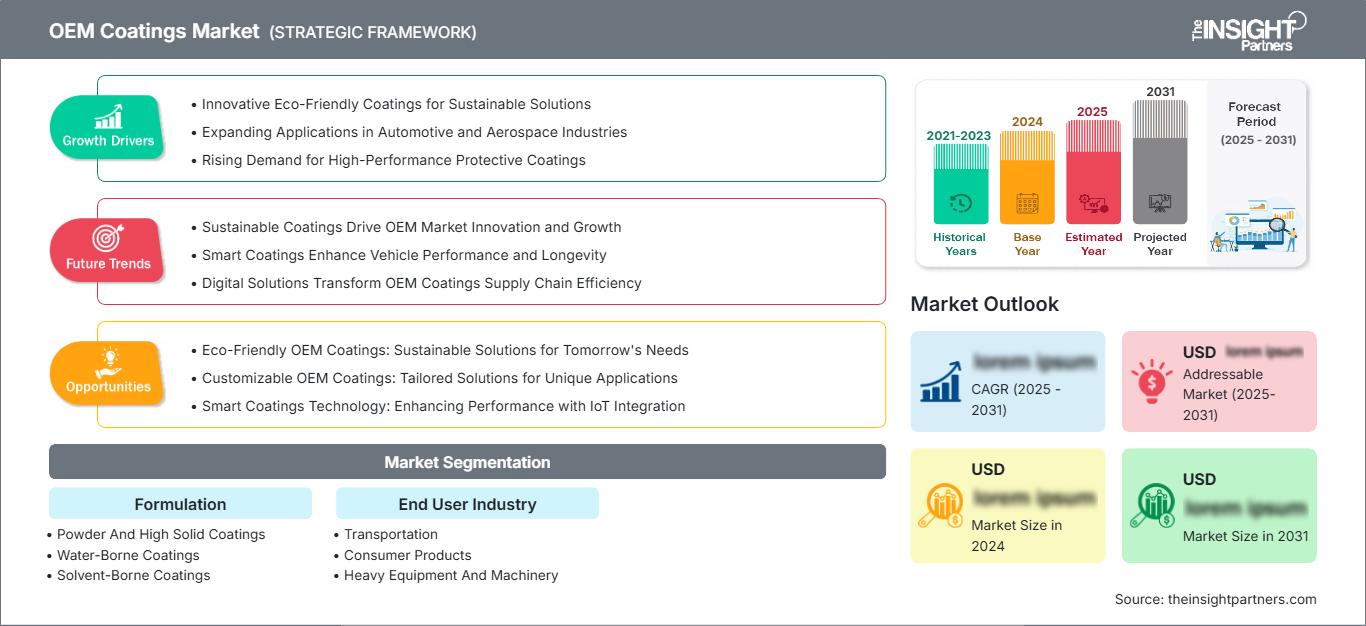
OEM Coatings Market: Strategic Insights
Regional Insights
North America oem coatings market
North America accounts for a 28–32% share in 2025 and is projected to grow at a 4.9–5.5% CAGR through 2034. Regional demand comes mainly from the United States and includes automotive assembly, commercial transportation, machinery, appliances, and industrial equipment. Mexico is also contributing with automotive and manufacturing supply chain. Domestic investment in production capabilities and infrastructure will support demand for coatings that have longevity and durability.
OEM customers are more interested in shorter curing times, high transfer efficiency, low VOCs, and consistent availability. Powder and high solids technologies are gaining relevance in the applications where suitable, while water borne coatings play an important role where lower solvent emission regulations apply. Technical service at local level is very important since coating qualifications are related to plant specific equipment and processes.
U.S. oem coatings Market
The US represents 80–84% of North American demand and is expected to grow at a 4.8–5.4% CAGR through 2034. The automotive industry, industrial machines, transport vehicles, appliances, and consumer products represent the primary customers. PPG Industries Inc., Axalta Coating Systems Ltd., BASF SE, The Sherwin-Williams Company, 3M Company, and The Valspar Corporation have considerable marketing power.
Current application needs are moving to coating applications that facilitate automation and minimize energy usage. Automotive plants are assessing low-temperature cure systems, waterborne basecoats, electrocoats, and superior clearcoats, while machinery companies are concerned about corrosion resistance and quick manufacturing time. Reshoring of the industrial sector could aid in increasing demand for coatings in the U.S., as new and expanded plants will need local supply.
Europe oem coatings Market
The oem coatings market report shows that Europe holds a 25–29% share in 2025 and is projected to expand at a 4.5–5.1% CAGR through 2034, with Germany leading. There is an additional demand coming from the UK, France, Italy, and Spain in terms of automotive production, industrial equipment, transportation, consumer goods, and machinery manufacturing. Regulation continues to be a major factor impacting the choice of formula and process investments.
Germany continues to be the key manufacturing hub in the region because the automotive production, machinery, and industrial equipment needs high performance coating systems. There is an increasing emphasis on demand for energy efficient applications and low-emission technology.
The UK has the combination of automotive, machinery, construction equipment, and industrial manufacturing needs. In France there is demand from transportation and aerospace manufacturing. In Italy and Spain there is demand for machinery, automotive components, appliances, and industrial equipment. Customers are increasingly concerned about VOC performance, energy usage, and environmental factors across Europe.
APAC oem coatings Market
APAC represents a 32–36% share in 2025 and is projected to grow at a 6.1–6.8% CAGR through 2034, led by China. Manufacturing operations for automobiles and electronics continue to be strong in Japan and South Korea, with India developing its manufacturing base in vehicles, machinery, and consumer products. Australia plays a role in providing industrial equipment and transportation solutions.
The most dominant country in terms of coatings is China, with a huge manufacturing network and OEM manufacturing. Industrial localization strategies in India and Southeast Asia are helping build capacities, with growing demands due to electrification and automation in the coating industry.
Middle East & Africa oem coatings Market
Middle East and Africa demand is supported by transportation equipment, industrial machinery, infrastructure-related manufacturing, and consumer products. Saudi Arabia and the UAE are leading Middle Eastern markets, while South Africa represents a major African manufacturing center. The region is projected to grow at a 4.8–5.7% CAGR through 2034.
Saudi Arabia benefits from industrial diversification and manufacturing investment, while the UAE combines transportation, machinery, and industrial development. South Africa contributes through automotive assembly and industrial equipment. Harsh climatic conditions increase the importance of corrosion resistance, UV stability, and durable finishes, particularly for transportation and heavy-equipment applications.
Segmentation Analysis
Formulation
According to the oem coatings market forecast, the Formulation segment is projected to expand at a 5.4–5.9% CAGR between 2026–2034. Formulation selection increasingly depends on VOC requirements, curing temperature, line speed, substrate compatibility, appearance, and total application cost. The market scope increasingly encompasses systems designed around complete production-process optimization rather than coating chemistry alone.
- Powder And High Solid Coatings benefit from lower solvent content, high material utilization, and opportunities to reduce application steps. They are strategically relevant for machinery, metal components, transportation equipment, and applications compatible with thermal curing.
- Water-Borne Coatings remain important where lower solvent emissions and established automotive application technologies are required. Their adoption is supported by regulatory pressures and continued development of formulations offering improved appearance, drying, adhesion, and corrosion protection.
- Solvent-Borne Coatings continue to serve applications requiring specific application characteristics, substrate compatibility, and established production processes. Their installed-base relevance supports demand where replacement costs or process changes make immediate technology conversion impractical.
- Radiation Curable Coatings offer rapid curing and reduced thermal requirements for suitable substrates and production configurations. Their strategic importance is increasing in specialized industrial and consumer-product applications where line speed and compact processing equipment are priorities.
End User Industry
The End User Industry segment is expected to grow at a 5.2–5.8% CAGR from 2026–2034. Transportation remains the largest demand pool, while consumer products and heavy equipment provide diversified opportunities. The oem coatings market analysis increasingly centers on end-user production efficiency and specialized substrate requirements.
- Transportation represents the largest application base because automotive, commercial vehicles, rail-related equipment, and other transport products require multi-layer coating systems for appearance, corrosion protection, durability, and long service life.
- Consumer Products encompass appliances, electronics, furniture-related products, and manufactured goods. OEM customers emphasize finish consistency, color accuracy, throughput, scratch resistance, and efficient curing to maintain product quality at high production volumes.
- Heavy Equipment And Machinery demand is linked to agricultural equipment, construction machinery, industrial equipment, and specialized vehicles. These applications typically require strong corrosion resistance, mechanical durability, chemical resistance, and coatings capable of withstanding demanding operating environments.
Opportunity Snapshot
| End User Industry | Revenue Contribution | Trend Tag | Adoption Stage |
| Transportation | High | EV Platforms | Scaling |
| Consumer Products | Medium | Smart Appliances | Mature |
| Heavy Equipment And Machinery | Medium | Fleet Electrification | Scaling |
OEM Coatings Market Growth Drivers and Impact Analysis
Vehicle Electrification Is Increasing Functional Coating Requirements
There is a need for coating systems that function under varied substrate surfaces, temperatures, electrical environments, and durability standards in electrified vehicles. The battery cases, the electric motor, light-weighted aluminum parts, and multiple material body structures are some of the features that have led to the emergence of new technical standards other than the steel bodied ones. Coating materials can help in corrosion prevention, electrical insulation, heat management, fire-retardance, and surface protection. This will increase the scope of the OEM coating supplier from a supplier of appearance products to a functional product supplier. There is also a trend towards increased complexity in qualification because the battery and power-electronic parts may lead to operating conditions that are different from traditional vehicle parts.
Manufacturing Productivity Is Increasing the Value of Process-Efficient Coatings
Coating suppliers have begun considering coating technologies by how much they contribute to total production efficiency versus price of material alone. Quicker curing, fewer application steps, higher transfer efficiency, less masking, and decreased rework will all help increase available plant capacity while decreasing energy and materials used. In particular, this is important for where paint lines are a bottleneck in production of automobiles and equipment. Therefore, coating suppliers have the motivation to create coatings that can be applied via automation, lower curing temperature, and tight process control. The customers are helped by those coating technologies that decrease line stops and increase first-pass yield. When manufacturing facilities are seeking a lean operation, coating suppliers who can show an improvement in processes have a stronger qualification position than those only offering better formulated prices.
Environmental Regulation Is Accelerating Reformulation and Technology Substitution
Increasing environmental regulations are leading OEM manufacturers to reassess their use of solvents, emissions, waste, and energy-intensive curing systems. This transition is not consistent as factors such as substrate, equipment, climate, product requirements, and existing plant facilities dictate the choice of technology. Water-based, powder, high solid, and radiation curable coatings are capable of handling certain sections of this transition. Reformulation makes the role of technical services more important as reformulation impacts viscosity, drying properties, adhesion, and appearance, among others. Suppliers that have customer qualification capability stand in a better position to help customers move to a new technology without interrupting production operations. Therefore, this regulation-induced substitution may result in replacement even where the volume of manufacturing operations remains constant.
OEM Coatings Market Future Trends
Digital Color Management Will Become More Integrated With Production
The oem coatings market trends indicate that digital color management is expected to become increasingly connected with formulation databases, automated dispensing, production monitoring, and quality-control systems. The automotive and consumer-product industries are both working on increasing consistency in manufacturing while also facing the need for reduced cycles and increased customization. Modern software can help minimize manual color corrections, increase formula consistency, and detect inconsistencies before there is major work involved in fixing them. The next step will probably be using digital color libraries in conjunction with predictive analytics, automated dispensing, and vision inspection. Manufacturers of coating materials can leverage these technologies to build stronger customer relations since the benefit goes beyond providing the paint but also the performance of the process itself.
Low-Temperature and Energy-Efficient Curing Will Gain Strategic Importance
Future coating development is likely to prioritize lower curing temperatures, shorter oven residence times, and curing methods compatible with heat-sensitive substrates. Energy-intensive paint-shop operations create a significant opportunity for technologies that reduce thermal requirements without compromising film performance. This trend will be particularly relevant as manufacturers introduce lightweight plastics, composites, aluminum structures, and mixed-material assemblies. Powder and high-solid systems may benefit where process conditions permit, while radiation-curable technologies can address specialized high-speed applications. OEM qualification will increasingly examine the complete energy profile of the coating process, including booth operation, curing, ventilation, and rework. Suppliers that quantify energy and productivity benefits alongside coating performance should have stronger prospects in future plant modernization programs.
OEM Coatings Market Opportunities
Localized Formulation Capacity in India and Southeast Asia
India and Southeast Asia present opportunities for suppliers to establish localized formulation, technical service, and application-development capabilities close to expanding manufacturing clusters. Automotive, consumer products, machinery, electronics, and transportation equipment production are increasing the need for consistent OEM coating supply. Local production can shorten lead times and improve responsiveness to customer-specific formulations while reducing exposure to international logistics disruptions. Suppliers can prioritize water-borne, high-solid, and powder technologies aligned with regional environmental requirements, while maintaining established solvent-borne systems for qualified applications. Partnerships with local OEMs and contract manufacturers can accelerate product qualification. Establishing regional laboratories is also strategically valuable because climate, substrate, process equipment, and production conditions can differ materially from those in established European or North American plants.
Specialized Coatings for Batteries and Mixed-Material Components
Battery systems, electric motors, lightweight structures, and mixed-material components are creating specialized coating requirements that extend beyond traditional exterior vehicle surfaces. Suppliers can target dielectric protection, corrosion resistance, thermal exposure, abrasion resistance, and fire-performance requirements for battery and power-electronics applications. These products can command greater technical differentiation because qualification depends on safety, reliability, and compatibility with complex component designs. Investment should focus on application laboratories, substrate testing, accelerated durability programs, and collaboration with component manufacturers. The opportunity also extends to heavy equipment and industrial machinery as electrification expands beyond passenger vehicles. Suppliers that establish early technical positions in these applications can participate in platform qualification before coating specifications become standardized across larger production volumes.
Recent Developments
- August 7, 2026: Nippon Paint Holdings Co., Ltd. announced the acquisition of shares in a European automotive coatings business, strengthening its automotive coatings platform and geographic reach. The transaction reflects the company's broader strategy of expanding automotive capabilities while integrating technical resources and customer relationships across its global operating structure.
- June 5, 2026: PPG Industries, Inc. Automotive OEM Coatings business presented battery-focused technologies at The Battery Show Europe 2026, covering thermal management, dielectric isolation, battery fire protection, repairability, and precision application. The initiative highlights increasing coating requirements associated with electrified vehicle architectures and battery manufacturing efficiency.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for