
EV Composites Market Trends, Demand & Growth by 2034
EV Composites Market Size and Forecasts (2021–2034), Global and Regional Share, Trends, and Growth Opportunity Analysis Report Coverage : by Fiber Type (Glass Fiber, Carbon Fiber); Resin Type (Thermoplastics, Thermoset); Type (Ultra-Premium, Premium and Non-Premium); and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00040497
- Category : Chemicals and Materials
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 15, 2026


2025 Market Size
US$ 3. Bn
Base year value
2034 Forecast
US$ 10.88 Bn
Projected by 2034
CAGR 2026-2034
15.39 %
Growth rate
Addressable Market
US$ 59.08 Bn
(2026-2034)
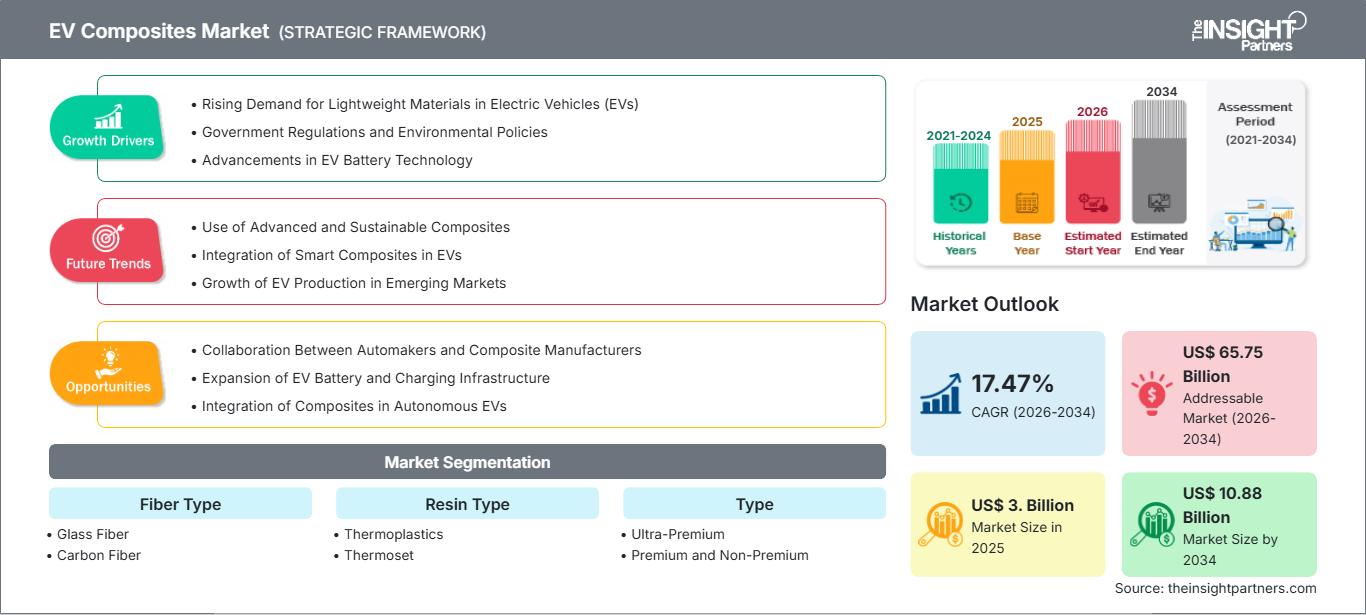
The EV Composites market was valued at US$ 3 billion in 2025 and is expected to reach US$ 10.88 billion by 2034; it is estimated to record a CAGR of 15.39% during 2026-2034.
EV Composites Market Assessment and Insights
- North America: North America represented an estimated 24–28% EV Composites Market share in 2025 and is projected to grow at a CAGR of 15–17% between 2026–2034, supported by EV platform localization, battery enclosure adoption, and lightweighting programs.
- US: The US accounted for 20–23% of the North American market in 2025 and is expected to expand at a 15–17% CAGR between 2026–2034, led by EV structural applications and battery protection.
- Europe: Europe held an estimated 25–29% share in 2025 and is projected to grow at a 16–18% CAGR between 2026–2034, with Germany, France, the UK, Italy, and Spain supporting demand through electrification and emissions compliance.
- Asia Pacific: Asia Pacific represented an estimated 34–38% share in 2025 and is expected to register a 19–21% CAGR between 2026–2034, led by China, Japan, South Korea, and India through high-volume EV manufacturing and materials localization.
- Largest Segment: Glass Fiber held an estimated 55–59% market share in 2025 and is projected to grow at a 16–18% CAGR between 2026–2034, reflecting its cost-performance balance.
- High Growth Segment: Thermoplastics held an estimated 38–42% market share in 2025 and is projected to expand at a 19–21% CAGR between 2026–2034, supported by recyclability and faster processing.
- Key companies analyzed in detail: Atlas Fibre, CIE Automotive India Limited, ElringKlinger AG, Envalior B.V., Euro Advanced Carbon Fiber Composites GmbH, Exel Composites Plc, Faurecia SE, HRC (Hengrui Corporation), IDI Composites International, Inc., Jiangsu Kangde Xin Composite Material Co., Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Car body design is evolving from high-metal assemblies towards an optimal blend of materials offering improved mass, stiffness, crashworthiness, thermal management, and manufacturing. EV composites are thus being utilized in not just body parts but also battery covers, protective casings, underbody shields, structural reinforcements, and electrical protection systems. Molded automation, hybrid composite-metal systems, and quick-cure processes have helped improve the economics of production as well as accommodate larger vehicle projects.
In the coming years, investments will be made in scalable thermoplastic systems, recyclable reinforcement, local compounding, and built-in battery systems. Manufacturing hubs in India and Southeast Asia will be gaining in significance for automakers who are looking to diversify sourcing, along with the sustainable standards of Europe that will make traceable materials and recoverable structures essential. There are also good prospects for North American manufacturers.
EV Composites Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 3. Billion |
| Market Size by 2034 | US$ 10.88 Billion |
| Global CAGR (2026 - 2034) | 15.39% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
EV Composites Market Analysis
EV Composites Market growth is highly dependent on the requirement to balance battery weight without adversely affecting safety and range capabilities. The composite value chain comprises the fiber, resins, compounds, laminates, moldings, tier one suppliers, and vehicle manufacturers. Glass fiber continues to play a significant role in cases where cost efficiency is of primary importance, while carbon fibers meet the requirements for stiffness and significant weight savings. Battery casings represent another application that adds volume, owing to the ability of composites to bring together structural, electrically insulating, corrosion resistant, and thermal management capabilities in one part.
The supply-side dynamics increasingly tend to favor those players that can merge material technology with component technology. Resin Transfer Molding (RTM), Compression Molding (CM), Injection Molding (IM) and Hybrid Molding offer diverse possibilities regarding the interplay between cycle times, surface quality, fiber content, and cost of the tooling. Manufacturing volume continues to be the key limitation, owing to the fact that automotive applications require reliable quality, fast cycle times, and competitive piece pricing.
According to the EV Composites Market report, there is fragmentation in terms of competition among companies such as material experts, Tier-1 automotive suppliers, compounders, and composite material manufacturers. ElringKlinger AG and Faurecia SE have their presence in the form of their vehicle system capabilities and lightweight component technologies, while Envalior B.V. offers engineered plastics and composite materials. The CIE Automotive India Limited has its presence through the manufacturing facilities available in India, while Exel Composites Plc offers pultrusion and composites processes technology to specialized applications.
Increasing focus on investment is being made in the area of application engineering rather than just fiber capacity. There is development of battery covers, panels, electrical components, and hybrids that can act as a substitute for several metallic components. Some of the leading companies offering capabilities in this market include Atlas Fibre, Euro Advanced Carbon Fiber Composites GmbH, IDI Composites International, Inc., HRC (Hengrui Corporation), and Jiangsu Kangde Xin Composite Material Co., Ltd.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
EV Composites Market: Strategic Insights
Regional Insights
North America EV Composites Market
North America held an estimated 24–28% share of the EV Composites Market in 2025 and is expected to grow at a 15–17% CAGR through 2034. It will be helped by increases in EV production, battery production and need for lighter parts. Composites are used mainly in the manufacture of batteries, underbody, body and insulation where rust-proofing and part integration offer clear engineering advantages.
North America is the key demand region with the US being the key demand driver. Canada and Mexico contribute to manufacturing capabilities due to their involvement in the supply chain of automobiles. Increasingly important will be local sourcing of composite manufacturers as manufacturers look to reduce logistic chains and have more control over material availability. Composites can take advantage of platform localization despite qualifications and competition from aluminum and advanced steel.
U.S. EV Composites Market
The US accounted for an estimated 82–86% of North America’s EV Composites Market in 2025 and is expected to grow at a 15–17% CAGR through 2034. The demand is concentrated in areas such as passenger EVs, electric pickup trucks, SUVs, and commercial vehicles where the weight, anti-corrosion nature, and protection of batteries affects the choice of materials for these vehicles.
The EV Composites Market forecast shows that development of applications has been increasingly geared toward products such as battery enclosures, coverings, electrical housings, and underbody parts. This would be aided by suppliers that have qualification capability in the automotive industry while domestic manufacturing and regional procurement limit exposure to international logistics.
Europe EV Composites Market
Europe represented an estimated 25–29% EV Composites Market in 2025 and is projected to expand at a 16–18% CAGR through 2034. Germany leads the rankings due to the extensive automotive engineering expertise that it has; it is followed by the UK, France, Italy, and Spain. Pressure from regulation and efficiency needs contribute to the use of advanced materials.
The UK has a focus on the high-end electric vehicle platforms, performance, and advanced manufacturing; the demand is for the high-performance composites. Germany brings in OEM engineering expertise coupled with Tier 1 capabilities and battery enclosure expertise. France has an advantage due to increased production and localization of EVs. Italy still has an opening in the high-performance vehicles and specialty components category.
APAC EV Composites Market
APAC held an estimated 34–38% share in 2025 and is expected to record a 19–21% CAGR through 2034. China is the largest market due to its robust volume production base for EVs, followed by Japan, South Korea, India, and Australia. Volume production, development of local materials, and batteries will drive the regional demand.
China will be the leader in volume production, whereas Japan and South Korea will focus on advanced material and engineering solutions. India is developing due to the local production of EVs and components, and Australia is still a small market but is relevant for special materials.
Middle East & Africa EV Composites Market
Middle East and Africa demand is smaller but increasingly supported by infrastructure modernization, vehicle diversification, and energy-transition investment. Saudi Arabia and the UAE are leading regional markets, while South Africa provides the principal automotive manufacturing base. The region is expected to expand at a 12–15% CAGR through 2034 as EV assembly and imported electric models broaden.
Saudi Arabia and the UAE provide opportunities through new mobility and industrial projects, while South Africa offers established vehicle manufacturing capabilities. The Rest of MEA remains dependent on charging infrastructure, import economics, and policy development. Composite demand should initially favor specialty components, lightweight body systems, and battery protection rather than highly integrated mass-market structures.
Segmentation Analysis
Fiber Type
Fiber Type is expected to expand at a 16–18% CAGR between 2026–2034. Material selection depends on vehicle price positioning, structural requirements, processing economics, and weight targets. Glass fiber retains broad automotive relevance because it balances performance and cost, while carbon fiber is increasingly selected where maximum stiffness and mass reduction justify higher material expenditure.
- Glass Fiber: Glass fiber maintains a broad market position because of favorable cost, impact performance, and established automotive processing routes. Demand is strongest in battery covers, structural panels, underbody parts, and semi-structural components requiring scalable production.
- Carbon Fiber: Carbon fiber remains strategically important for premium and performance-oriented EVs where stiffness-to-weight performance has greater value. Adoption is expanding into structural components and battery-related applications as production technologies improve.
Resin Type
Resin Type is projected to grow at a 18–20% CAGR between 2026–2034. Resin selection increasingly reflects processing speed, thermal stability, recyclability, joining requirements, and component geometry. Thermosets remain established in structural applications, while thermoplastics are gaining momentum through rapid processing, weldability, and potential material recovery advantages.
- Thermoplastics: Thermoplastics are gaining strategic importance in high-volume EV production because they support shorter processing cycles, welding, repairability, and potential recyclability. They are particularly relevant to battery covers, electrical housings, and semi-structural assemblies.
- Thermoset: Thermosets retain strong demand where dimensional stability, heat resistance, fiber impregnation, and structural integrity are priorities. Their established processing infrastructure supports continued use in battery enclosures, structural components, and demanding body applications.
Type
Type is projected to expand at a 17–19% CAGR between 2026–2034 as composite adoption moves progressively from high-priced performance vehicles toward broader EV platforms. Pricing, production scale, fiber selection, and automation will determine the pace at which composite components penetrate each vehicle class.
- Ultra-Premium: Ultra-Premium vehicles prioritize weight reduction, stiffness, performance, and design freedom, allowing higher composite content where engineering benefits outweigh material and tooling costs.
- Premium: Premium EV programs provide a significant adoption base because customers value range, performance, styling, and advanced structures. Composite components can justify higher material costs through functional integration.
- Non-Premium: Non-Premium vehicles require strict cost control, making glass fiber, thermoplastics, hybrid designs, and high-throughput molding particularly important for wider composite penetration.
Opportunity Snapshot
| Type | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
|---|---|---|---|
| Ultra-Premium | Medium | Structural CFRP | Mature |
| Premium | High | Battery Lightweighting | Scaling |
| Non-Premium | High | Cost-Optimized GFRP | Scaling |
EV Composites Market Growth Drivers and Impact Analysis
Battery Weight Reduction and Vehicle Range Optimization
Battery packs add substantial mass to electric vehicles, increasing the value of lightweight structural materials throughout the vehicle architecture. Weight savings of 10% would result in approximately a 4-6% increase in EV range, allowing material substitution to become an economic factor when taking battery pricing and pack configurations into account. Composites would allow the combination of rigidity, impact resistance, electrical insulation, and corrosion protection in fewer parts. This opens up applications in the areas of battery enclosure, underbody protection, cross members, and strengthened body structures. It is not just the effect on range that allows for a commercial opportunity, since less weight allows the structure to be more forgiving in terms of the strain on the suspension, brakes, and chassis.
High-Voltage Safety and Integrated Battery Structures
Increasing battery voltages and power densities will increase the need for thermal stability, electrical insulation, flame retardancy, and dimensional stability. Composite solutions can deliver on multiple aspects of these needs, especially in cases where reinforcing thermoplastic materials or engineered thermosets are used together with specific barrier systems. Market penetration will be highest in battery housings, bus bar protection, electrical housings, and covers that are subjected to thermal cycling. In addition, there is the possibility of reducing assembly steps and enhancing sealing solutions through component integration. As electric vehicle architectures shift towards structural battery integration, the competitive position of composite companies will be determined by the performance of the entire system, not only its material properties.
Automation and Scalable Composite Manufacturing
There were concerns about automotive composite processing with regards to cycle times, tooling cost, and consistency in the past, although the use of automated compression molding, injection molding, RTM, and hybrid technologies is helping to scale up. Quick curing technology and thermoplastic forming may help to increase production capacity while minimizing manual intervention. The impact on commercialization is substantial since it all depends on the economics of production to decide whether automotive composites would remain in the realm of luxury cars only or make their way into mass produced electric vehicles. Automated inspection and digital process control can additionally minimize scrap and ensure dimensional accuracy. Those suppliers willing to invest in high throughput machinery would be well positioned for bigger projects, especially those combining development of materials and components together.
EV Composites Market Future Trends
Thermoplastic Composite Battery Enclosures
The EV Composites Market trends show that thermoplastic composite battery enclosures are likely to become a major development pathway as OEMs seek faster production, lower component mass, and improved end-of-life options. Future designs will increasingly combine continuous and discontinuous reinforcement within multilayer architectures, allowing local stiffness to be tuned around crash and mounting zones. Hybrid molding can integrate ribs, inserts, fastening features, and electrical protection in fewer manufacturing stages. Material suppliers are also expected to expand flame-retardant and low-smoke formulations suitable for high-voltage environments. As battery platforms become standardized across vehicle families, enclosure designs should become more modular, creating repeatable opportunities for qualified composite suppliers. Recyclability, traceable material content, and compatibility with automated joining processes will increasingly influence platform-level material selection.
Multifunctional Composite Structures
Future composite architectures will increasingly combine structural, thermal, electrical, and aerodynamic functions within the same component. Battery covers may incorporate thermal barriers and crash reinforcement, while underbody panels can provide stiffness, airflow management, and impact protection. Such multifunctionality can reduce component count and assembly complexity, creating a stronger economic case than simple weight substitution. Development programs are likely to use simulation-driven design to optimize fiber orientation, resin distribution, crash response, and heat management simultaneously. The result should be greater adoption of hybrid laminates and locally reinforced structures across premium and mainstream platforms. Suppliers with application engineering capabilities will therefore have an advantage over companies offering commodity materials without design support.
EV Composites Market Opportunities
Localized Composite Manufacturing in Emerging EV Hubs
India and Southeast Asia offer strategic opportunities for composite manufacturers as vehicle production and battery supply chains become more geographically diversified. Local production can reduce freight exposure, shorten qualification cycles, and enable suppliers to customize formulations for regional vehicle platforms. Investment opportunities extend from glass-fiber compounding and thermoplastic molding to automated structural component production. Partnerships with Tier-1 suppliers can accelerate market entry by providing access to established automotive validation systems. India is particularly relevant for cost-sensitive EV platforms where glass fiber and thermoplastic composites can deliver practical lightweighting without the economics of extensive carbon fiber usage. Investors should prioritize facilities capable of serving multiple OEM programs and flexible enough to process different resin and reinforcement combinations.
Composite Recycling and Low-Carbon Material Platforms
Sustainability requirements create an opportunity to differentiate through recycled reinforcement, recyclable thermoplastic matrices, and verified product-level environmental data. European vehicle sustainability rules are increasing attention on material traceability, recoverability, and lifecycle performance, while global OEMs are setting their own carbon-reduction targets. Composite suppliers can capture value by developing materials that maintain mechanical performance while incorporating recycled content or lower-carbon feedstocks. The opportunity extends beyond material sales to take-back systems, reprocessing partnerships, and design-for-disassembly engineering. Companies able to provide credible lifecycle evidence alongside consistent automotive-grade performance may gain preferred-supplier status. Over time, circular material platforms could also reduce exposure to virgin resin and fiber price volatility.
Recent Developments
- July 2026: AZL, a German composites engineering group, launched a collaborative project to make plastic-based battery casings economically viable for electric trucks, buses and off-highway vehicles. Plastic casings are already used in passenger cars as an alternative to steel and aluminum, where AZL says they cut weight and open new routes to lower cost. The new Joint Partner Project, “Scaling Composite Battery Casings,” will focus on applying those gains to commercial vehicles, which have much lower production volumes per model.
- May 2025: Tata AutoComp Systems Ltd., a leading Indian automotive components manufacturer, and Katcon Global, a leader in exhaust systems, thermal insulation and advanced materials components, announced a new joint venture in Mexico to manufacture advanced composites, with a focus on serving the North American market. The venture will specialize in lightweight applications for passenger and commercial vehicles, agricultural tractors, off-road vehicles, and specialized non-automotive segments.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for